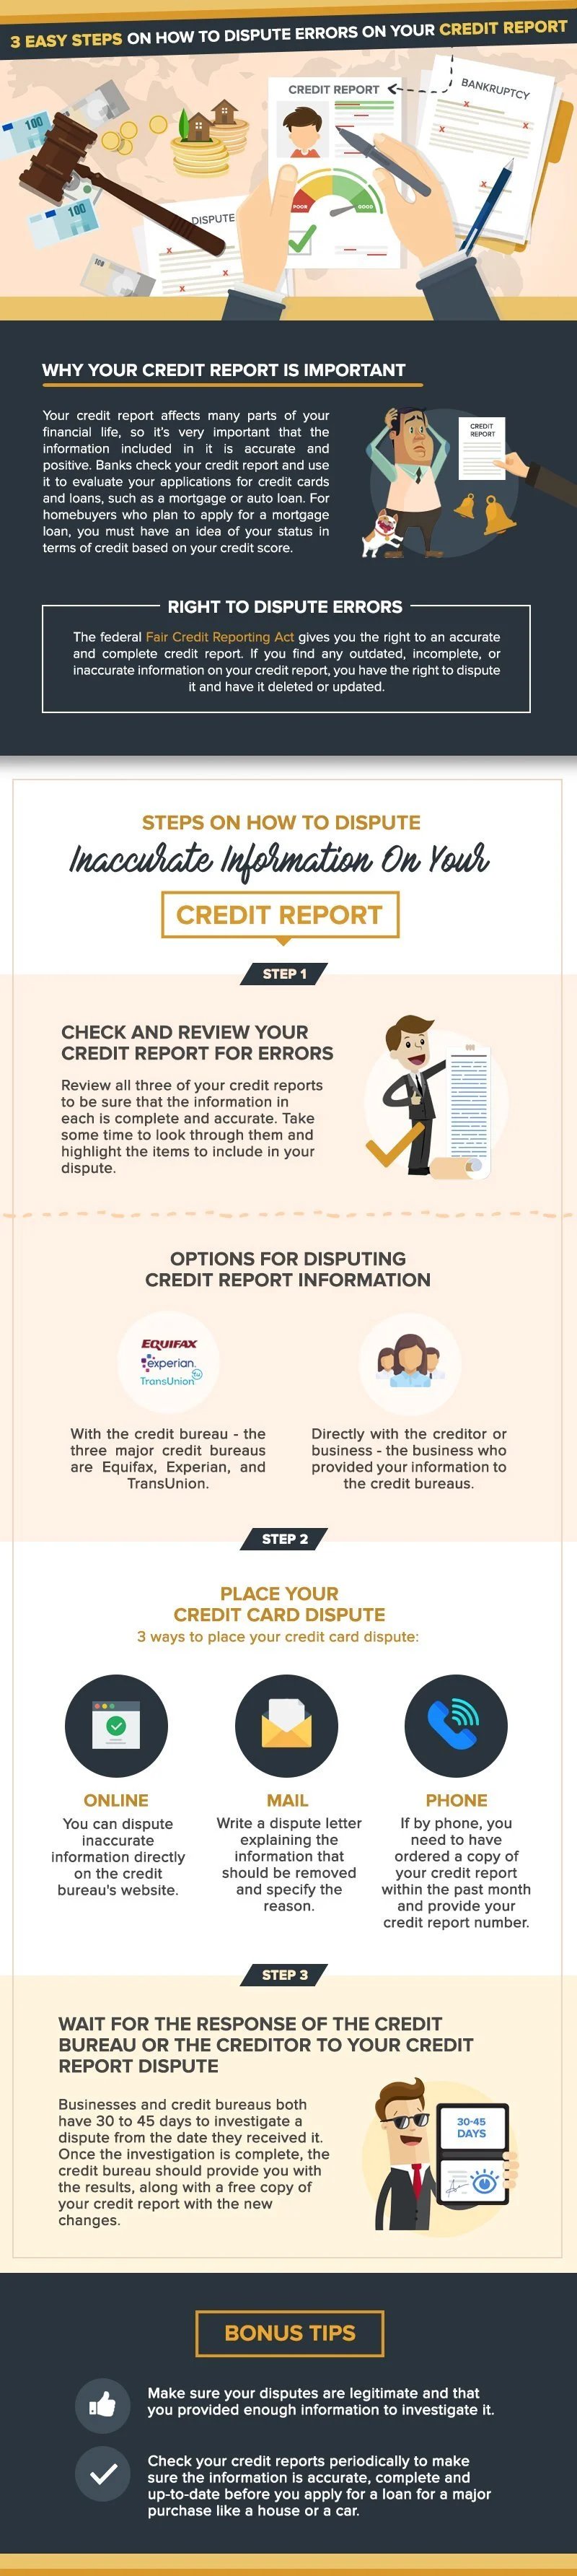
3 Easy Steps On How To Dispute Errors On Your Credit Report
Buyer January 19, 2018
Buyer January 19, 2018
Why Your Credit Report is Important
Your credit report is the sole source of information for your credit score — a number that lenders sometimes use instead of or in addition to your credit report. A variety of businesses may also view your credit report to make decisions related to you. Banks check your credit report and use it to evaluate your applications for credit cards and loans, including a mortgage or auto loan.
Especially for homebuyers who plan to apply for a mortgage loan, you must have an idea of your status in terms of credit based on your credit score. For renters, even landlords may review your credit report to decide whether to rent you. Hence, your credit report affects many parts of your financial life, so it's important that the information included is accurate and positive.
Right To Dispute Errors
However, it's very common for credit reports to contain errors, and these occur for a number of reasons. Some of the information that could mistakenly end up on your credit report can be anything from inaccurate late payments, to even a falsely reported bankruptcy.
As of 2017, the Consumer Financial Protection Bureau (CFPB) had handled approximately 185,700 credit reporting complaints . Some of those submitted by consumers include problems disputing complaints on their credit reports, complaints about inaccurate information on credit reports, and reports of confusion about credit scoring.
The federal Fair Credit Reporting Act gives you the right to an accurate and complete credit report. If you find any outdated, incomplete, or inaccurate information on your credit report, you have the right to dispute it and have it deleted or updated.
Steps On How To Dispute Inaccurate Information On Your Credit Report
1. Check and review your credit report for errors
The best way to find any inaccurate information on your credit report is to check a copy of it. There are several ways that you can get a copy. You can even get a free annual credit report from each bureau through the AnnualCreditReport.com, or order one directly from the bureau.
Once you have your credit reports, you should review all three of them to be sure that the information in each is complete and accurate, since you’ll never know which credit report will be used in a lending decision. Take some time to look through them and highlight the items to include in your credit report dispute.
Credit Report Errors You Can Dispute
You can dispute credit report items that are inaccurate, incomplete, out of date or that which cannot be verified. It can vary from minor and innocuous errors such as a misspelled name, an old address, birth date or your social security number. However, other errors could be detrimental to your credit score and could potentially cost you tens of thousands of dollars.
Negative items should only appear on your credit report for seven years, except bankruptcy, which can remain for ten. Thus, you can dispute any negative entries you have that are older than seven years. Other specific things you can dispute include but may not be limited to: payments reported late that were actually on time, accounts that aren’t yours, inaccurate credit limit/loan amount or account balance, inaccurate creditor, and inaccurate account status.
Options for Disputing Credit Report Information
2. Place your credit card dispute
Here are 3 ways to place your credit card dispute:
Online - Disputing credit report errors online is probably the most convenient way. You can dispute inaccurate information directly on the credit bureau's website. Each credit bureau should provide a way to upload, fax, or email documentation supporting your dispute. You can also check the status of your dispute online by providing your confirmation number. However, you can only get the results online and not by mail.
3. Wait for the response of the credit bureau or the creditor to your credit report dispute
Businesses and credit bureaus have the same amount of time to investigate a dispute — 30 to 45 days from the date they received it. Once the investigation is complete, the credit bureau should provide you with the results, along with a free copy of your credit report if there had been some changes. If they don’t respond in that time frame, you have the right to sue in Federal court for up to $1,000.
Bonus Tips:
Check your credit reports periodically. Financial advisors and consumer advocates suggest that you review your credit report periodically to make sure the information is accurate, complete, and up-to-date before you apply for a loan for a major purchase like a house or car, buy insurance, or apply for a job. Likewise, when applying for a mortgage loan, improving your credit score will give you a better chance to get pre-approved, which is the first step in purchasing your dream home.
Understand the pros and cons of interest-only mortgages to determine if this financing strategy is the right fit for your home buying goals.
In Houston, the question is often not “Should I wait?” It is “What is waiting likely to cost me, and is that tradeoff actually worth it?”
The right strategy depends on your finances, your comfort level, and how competitive the market is in the area where you are buying and selling.
Discover why your driveway is a critical component of your home's curb appeal and how simple updates can boost your property's market value.
Discover why outdoor living spaces are a top priority for luxury home buyers in Houston and how they can transform your property's appeal.
Don't let landscaping costs surprise you. Learn the essential maintenance expenses every home buyer should factor into their budget.
Learn the real reasons homes sit on the market and what sellers can do to attract buyers and sell faster in 2026.
Homeowner
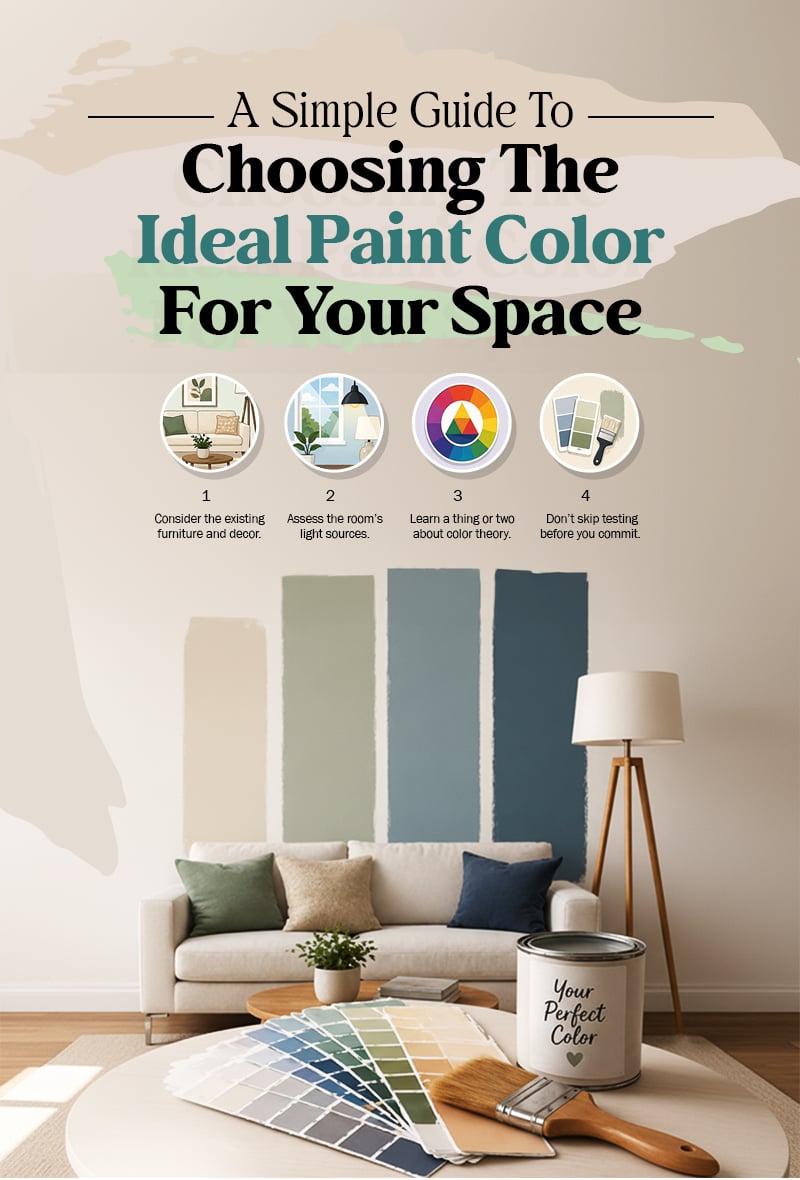
Selecting the ideal paint color can easily transform any space, creating a mood and style that reflects your personality and the room's purpose.
Deciding between repairs and selling as-is? Learn how to maximize your home's value and protect your peace of mind before listing in Houston.
Real estate can feel overwhelming, but you don’t have to navigate it alone. Our team is here to bring clarity to the process, advocate for your goals, and guide you every step of the way.
KRAASE PROPERTY GROUP
1220 AUGUSTA DR HOUSTON, TX 77057