5 Reasons Why A 30-Year Mortgage May Be The Right Choice For You
February 15, 2024
February 15, 2024
If you're a home buyer deciding between getting a 15-year and a 30-year mortgage, there’s a great chance that you’ve already consulted with friends and family, and may even have done tons of research online. You know that there are pros and cons for each type of mortgage, and that the 15-year mortgage is technically the cheaper alternative since you’ll be paying smaller interest rates. There are indeed a lot of practical reasons for choosing a 15-year loan, but you shouldn’t feel guilty for wanting to commit to 30 years of relatively small monthly payments instead. There’s a reason why the 30-year mortgage remains the most popular financing option among home buyers.
There are a lot of reasons why a 30-year mortgage can be just as good or even better than its 15-year counterpart. Depending on how efficiently you handle it, you’ll see that there are many ways you can take full advantage of a 30-year loan.
Buying a home may be one of the most significant achievements of adulthood, but it isn't the only goal for a lot of people, including you.
One of the main advantages of a 30-year mortgage is its relatively low monthly payment — and even if you know that you'll technically be paying more for your house in the long run, lower monthly fees allow you to free up funds to pursue other goals.
The extra money that isn’t going to paying off your house can be used for other worthwhile investments such as pursuing higher education, setting up a business, or buying your very first car. If you’re someone who believes in working on multiple goals simultaneously, then a 30-year mortgage can aid you in achieving them more comfortably.
With careful planning and consultation with your lender, you can take advantage of the safety of a 30-year mortgage with one of the main benefits of a 15-year mortgage - which is claiming full ownership of your home quickly.
You can start working on some strategies to pay off your mortgage early if -- during the 30 years of your mortgage— you feel that you're growing more capable of settling your debt. Ask your lender for an amortization schedule that can help you come up with a plan to own your home fully within the new timeline of your choosing.
The great thing about 30-year mortgages is that no matter what happens, you can be sure that your interest rate stays the same for the full 30-year term unless you sell or refinance the home.
Having a fixed mortgage rate will give you a sense of stability and will allow you to be more certain about the money you can use to build up your savings.
The lower monthly payments associated with a 30-year mortgage will allow you to buy more house than you could afford with a 15-year loan.
If you firmly believe that the perfect home for you and your family is one that you can only comfortably afford by stretching out payments over an extended period, then you're better off taking a 30-year loan.
Because monthly payments for a 30-year loan are relatively low as compared to payments for 15-year loans, you'll have a better chance at saving up for a rainy day.
If you follow a strict budget and are disciplined enough to set aside a fixed amount to grow your emergency fund, you're likely to feel more secure about your choices.
15-year mortgages require monthly payments that are at least 50% higher than those of 30-year mortgages. On top of this, there are also property taxes and insurance to worry about -- not to mention mortgage insurance premiums for those who put less than a 20% down payment. With all of these on your plate, high monthly fees would make it difficult for you to build an emergency fund or even respond to emergencies and other unexpected expenses. This may leave you with no choice other than to sell, refinance, or foreclose.
Understand the pros and cons of interest-only mortgages to determine if this financing strategy is the right fit for your home buying goals.
In Houston, the question is often not “Should I wait?” It is “What is waiting likely to cost me, and is that tradeoff actually worth it?”
The right strategy depends on your finances, your comfort level, and how competitive the market is in the area where you are buying and selling.
Discover why your driveway is a critical component of your home's curb appeal and how simple updates can boost your property's market value.
Discover why outdoor living spaces are a top priority for luxury home buyers in Houston and how they can transform your property's appeal.
Don't let landscaping costs surprise you. Learn the essential maintenance expenses every home buyer should factor into their budget.
Learn the real reasons homes sit on the market and what sellers can do to attract buyers and sell faster in 2026.
Homeowner
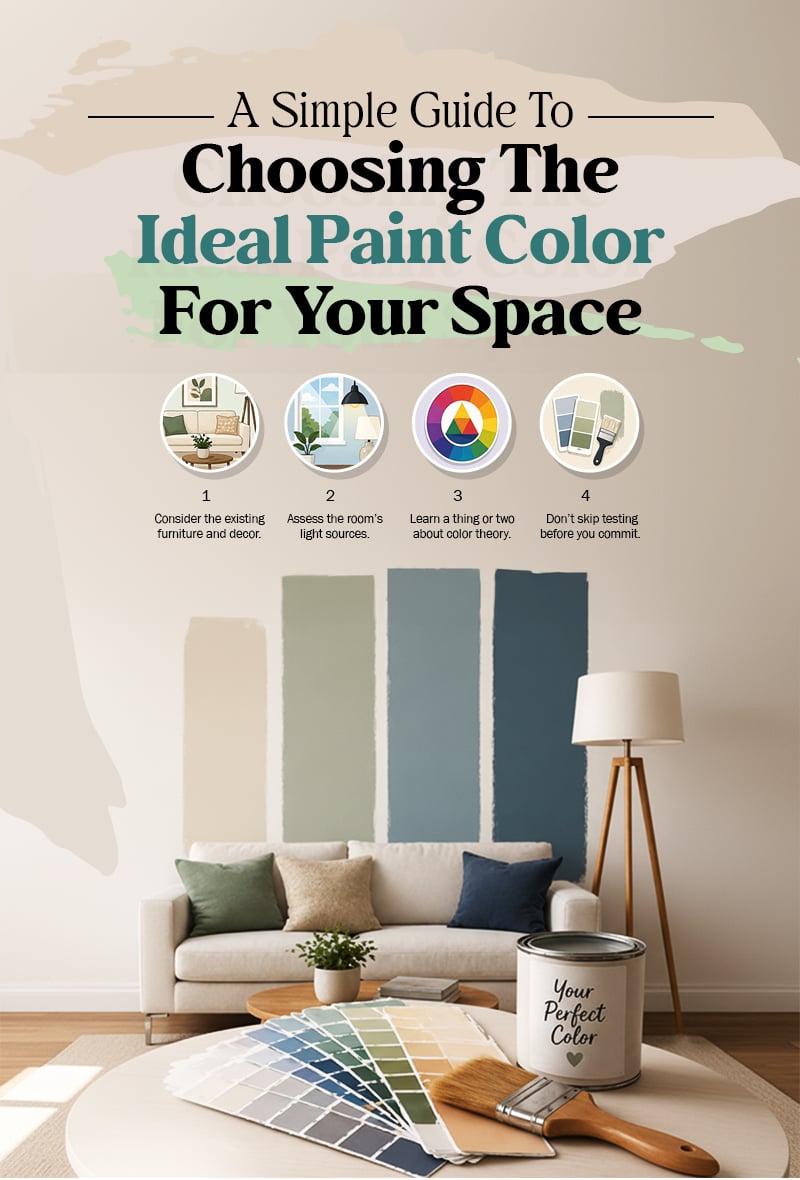
Selecting the ideal paint color can easily transform any space, creating a mood and style that reflects your personality and the room's purpose.
Deciding between repairs and selling as-is? Learn how to maximize your home's value and protect your peace of mind before listing in Houston.
Real estate can feel overwhelming, but you don’t have to navigate it alone. Our team is here to bring clarity to the process, advocate for your goals, and guide you every step of the way.
KRAASE PROPERTY GROUP
1220 AUGUSTA DR HOUSTON, TX 77057