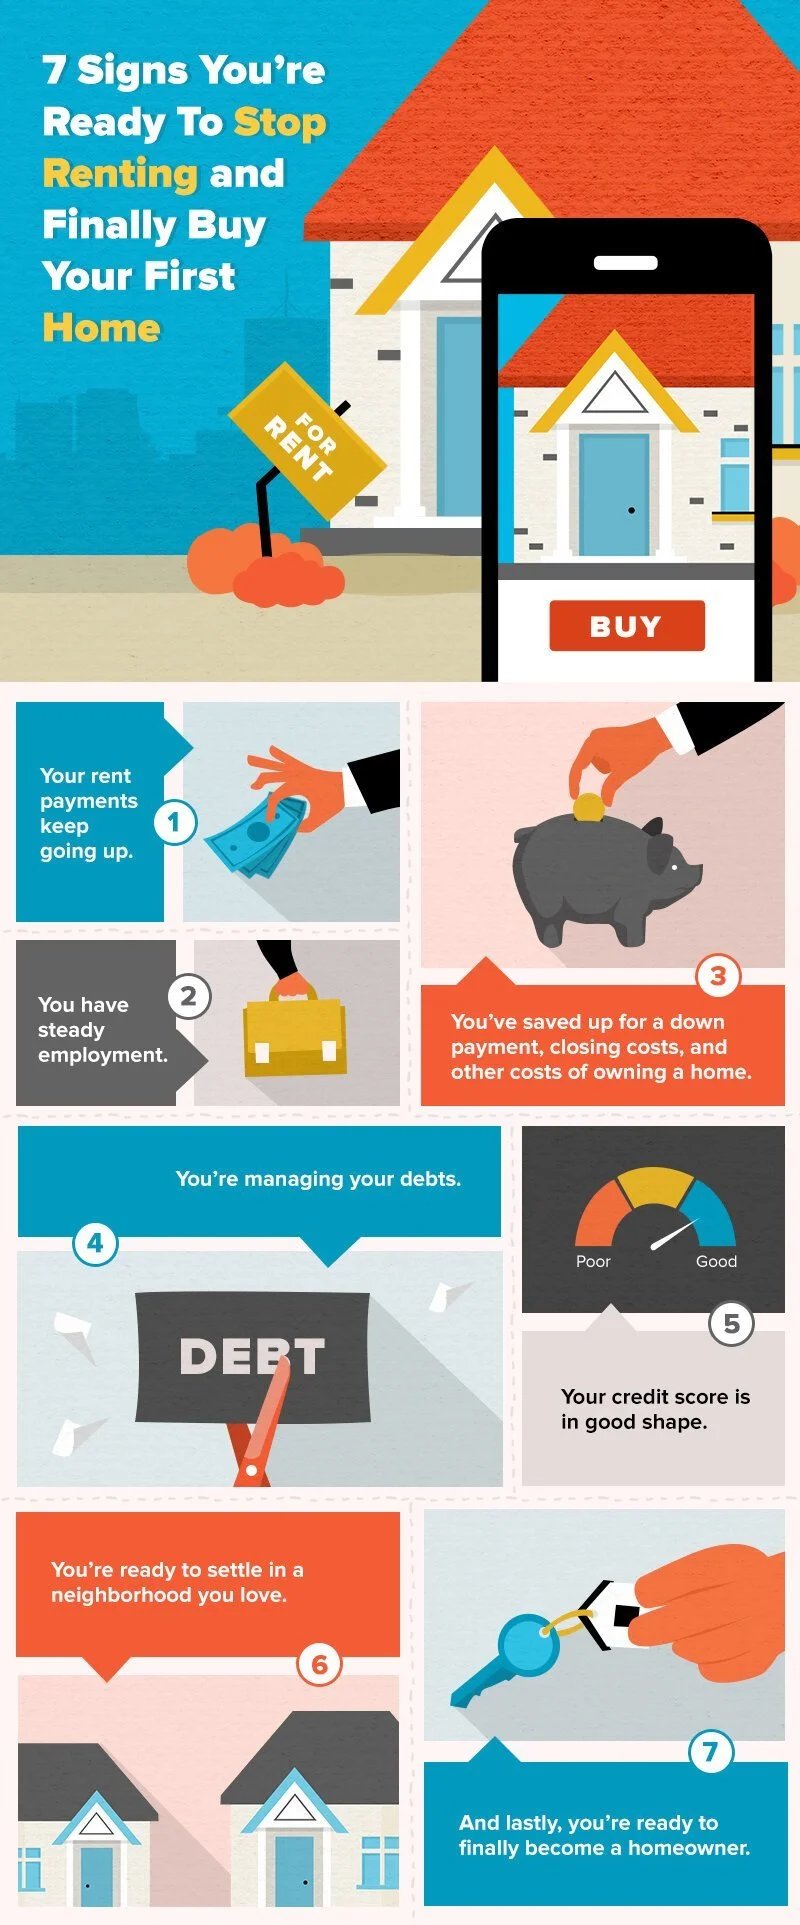
7 Signs You're Ready To Stop Renting and Finally Buy Your First Home
Buyer January 13, 2020
Buyer January 13, 2020

Rents keep on escalating in many parts of the country, and this is one of the biggest reasons why any renter would want to buy a home. In some neighborhoods and real estate markets, the cost of renting is even higher than the average monthly mortgage of a single-family home. If you already feel trapped with the uncertainty of your rent payments, you might be better off purchasing a home where your mortgage is consistent, and you'll be gradually putting equity into your biggest asset.

Employment plays a huge role in the mortgage application process since lenders and mortgage companies take into account your employment history before approving you for a loan. Typically, they would want to see that you spent at least two years working for the same company or in a similar field, and that you'll likely continue having the funds to pay your debt. If you’re a freelancer or a gig economy worker, you need to prove that you have a steady source of income for a couple of years through your W-2s, tax returns, and other documents. Just remember that for lenders, a stable job means a stable income, which lowers your risk as a borrower.

For many home buyers, the most difficult step in the home buying process is saving for a down payment, according to the 2019 NAR Profile of Home Buyers and Sellers. Setting aside money for a down payment towards their dream home is made even harder because of student loans and credit card debts. So if you have a stable job for a while now and your income has improved, there's a better chance for you to save up enough extra money to cover up the added expenses of homeownership.
And remember that the 20 percent down payment requirement for you to qualify for a mortgage is already a myth. In fact, mortgage insured by the Federal Housing Administration, also known as FHA loans, require only 3.5 percent of the home’s purchase price. Meanwhile, government loans guaranteed by the U.S. Department of Veterans Affairs (VA Loans) and the U.S. Department of Agriculture (USDA Loans) require no down payment at all, so there’s no need to scrape all your money just to cover the 20 percent down payment if it means leaving zero balance in your savings.
You know you’re ready to get the keys to your new home instead of renewing your lease if you have also saved up for closing costs and other homeownership expenses, such as property taxes, maintenance funds, and homeowner’s insurance.

It isn't necessary for you to be totally debt-free when you apply for a mortgage. Loan companies simply need to make sure that you aren’t carrying too much debt compared to what you make, and that you’ll be able to afford to take on additional responsibility, such as your potential monthly mortgage payment. They do this by determining your debt-to-income (DTI) ratio, which measures how much of your monthly income goes toward paying off your debts.
Lenders ideally prefer a ratio lower than 36 percent, but borrowers with no more than 43 percent DTI ratio can still get qualified for a home loan. Getting your debt down to a more manageable level will help put you in a stronger position to get pre-approved. Assess your spending habits even while still renting, and change them as much as possible to improve your chances of finally owning your first place.

One of the biggest reasons why renters can't make the leap to owning a home is because of their low credit score. Having good credit matters because it will determine how much money you can borrow and how much you’ll pay in interest. A good FICO score is usually about 690 and higher, although borrowers with a credit score as low as 500 can already qualify for a mortgage depending on the loan program.
When was the last time you’ve checked your credit report? If your credit is looking healthier because you’re making timely payments and settling your debts, you can have access to more conventional loan programs with lower down payments. Once you have addressed this important issue, you can rest assured that homeownership is now within your reach.

This one's quite subjective, but your preferred location and your capability to settle in one place are also huge considerations when buying your first home. If you anticipate moving in a few years, you know that you’ll only live in a particular area for a year or two, or you just can’t imagine yourself being tied down in one place, renting is likely your best option since you can leave whenever you want. Renting is also your smarter bet if you want to test out the waters in different areas where you’re thinking of buying a place.
But once you’re ready to settle down in a neighborhood you love, you’re secured in your job, and that you can see yourself putting down roots in the next five years, purchasing a home is your next sensible step.

In the 2019 Home Buyers and Sellers Generational Trends Report by the National Association of RealtorsR, 29 percent of all buyers cited their main reason for purchasing was the desire to own a home. Your readiness to become a homeowner matters above everything else. When you own a property, you'll be in charge of all the repairs, maintenance, and upkeep costs. If you’re not comfortable with these tasks and you’d rather leave the problem to a landlord, you may be better off renting for longer. Many people simply prefer to rent instead of taking advantage of lower interest rates because of this reason.
If the idea of home maintenance no longer intimidates you, you actually enjoy fixing things up in your place, and you’re ready to stay for the weekends just to mow the lawn and do other yard work, these are signs that you’re finally ready to call a place your home. You know you’re ready for the huge responsibility that is homeownership and you’re ready to be your own landlord.
Understand the pros and cons of interest-only mortgages to determine if this financing strategy is the right fit for your home buying goals.
In Houston, the question is often not “Should I wait?” It is “What is waiting likely to cost me, and is that tradeoff actually worth it?”
The right strategy depends on your finances, your comfort level, and how competitive the market is in the area where you are buying and selling.
Discover why your driveway is a critical component of your home's curb appeal and how simple updates can boost your property's market value.
Discover why outdoor living spaces are a top priority for luxury home buyers in Houston and how they can transform your property's appeal.
Don't let landscaping costs surprise you. Learn the essential maintenance expenses every home buyer should factor into their budget.
Learn the real reasons homes sit on the market and what sellers can do to attract buyers and sell faster in 2026.
Homeowner
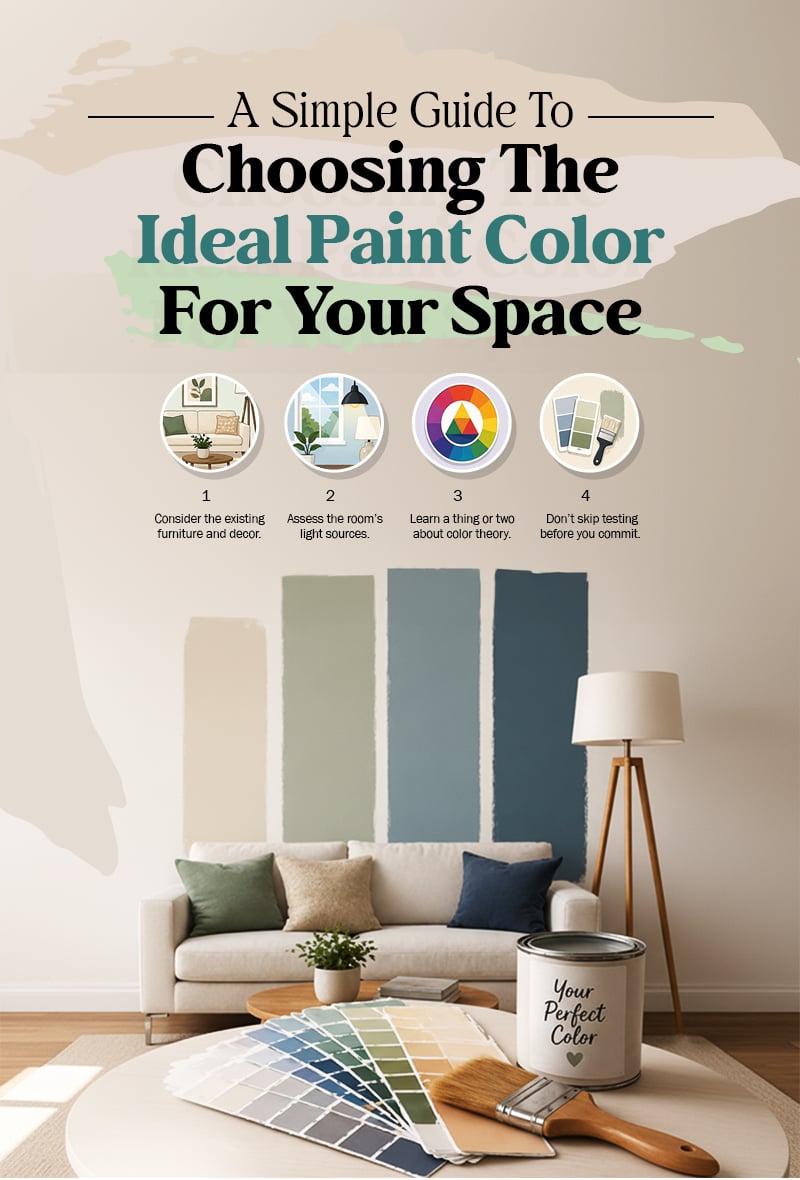
Selecting the ideal paint color can easily transform any space, creating a mood and style that reflects your personality and the room's purpose.
Deciding between repairs and selling as-is? Learn how to maximize your home's value and protect your peace of mind before listing in Houston.
Real estate can feel overwhelming, but you don’t have to navigate it alone. Our team is here to bring clarity to the process, advocate for your goals, and guide you every step of the way.
KRAASE PROPERTY GROUP
1220 AUGUSTA DR HOUSTON, TX 77057