A First-Time Home Buyer's Guide to Down Payment Assistance Programs
February 16, 2024
February 16, 2024
What is the most difficult part of buying a home? For many first-time buyers, their biggest hurdle is coming up with enough money for the down payment. In the National Association of Realtors® 2019 Profile of Home Buyers And Sellers, buyers cited that student loans, credit card debt and car loans make saving for a down payment difficult.
A down payment is a portion of the total sales price of the home you will purchase, and is typically expressed as percentages. It will be given directly to the seller while the rest of the payment comes from your mortgage (unless you're buying with cash). The median down payment for homes purchased in 2018 was around 6 percent, but putting in at least 20 percent down lets you avoid paying for private mortgage insurance or PMI.
So how can you scrape together thousands of dollars to finally hold your first set of house keys? The good news is that there are plenty of down payment assistance programs available to help buyers overcome this huge financial hurdle.
Down payment assistance is any program or funding option, such as grants, zero-to-low-interest loans, and tax credits for eligible home buyers. They provide funds to help them pay for the down payment or cover closing costs. Most of these programs are managed and funded by the federal, state or local governments, each with its own requirements and limitations. You can work with any participating lenders who are trained on the program guidelines to apply and access these aids, or you can directly contact the government agency that’s offering the program.
Here are some of the most common requirements of down payment assistance programs and low-down payment loans:
1. Available to first-time homebuyers
Did you know that you can qualify as a “first-time” home buyer even if you've owned a house before? You are considered eligible to apply for first-time home buyer loans and benefits if you haven’t owned your principal residence in the last three to five years. So, if you owned a home in the past but are renting now, don’t just count yourself out and make sure to check how your target program defines the term.
The FHA Loans insured by the Federal Housing Administration (FHA), an agency within the U.S. Department of Housing and Urban Development (HUD), greatly benefit first-time homebuyers who have little or no money saved for a down payment and have lower credit scores.
2. Income requirements
Most assistance programs are intended only to serve residents with low-to-moderate-income. Sometimes, a borrower's household income must also be below a certain threshold in order to qualify for assistance.
The Rural Development Single Family Housing Guaranteed Loan Program offered by the U.S. Department of Agriculture, or USDA loans, have adjusted household income limits that vary per state and city.
3. Residence restrictions and location
Other programs will only allow buyers to purchase homes in an approved location or in certain areas. Many cities even offer forms of assistance in order to attract residents to live and work in the area for a given time period.
For the USDA loans, borrowers must buy in areas with a population below 35,000, which includes many rural and some suburban areas. Meanwhile, the Good Neighbor Next Door (GNND) Program sponsored by the HUD, is designed to encourage the purchase of homes located in “revitalization areas” or those neighborhoods that have low household incomes and many foreclosed properties.
4. Home price limits
Many assistance programs also limit the price of the home you can buy, which is usually a percentage of an area's median home purchase price. Home price limits sometimes also vary for existing homes and new construction.
5. You need to live in the home for a set number of years.
Borrowers who wish to use down payment assistance may also be required to live in the homes they purchase for a set number of years, usually for at least five years. If you sell your home before the set number of years, you will have to pay back the assistance you received on a prorated basis.
6. Some are only available to buyers of certain professions.
Your occupation can also be the key to owning your dream home. There are separate programs intended to serve specific professionals such as educators, protectors, firefighters, veterans, and households with disabled members.
The home loans offered by the U.S. Department of Veterans Affairs (VA) allow veterans, active-duty service personnel, and select Reservists or National Guard members, as well as the spouses of military members, to own a piece of the American dream by requiring no down payment and competitive rates.
The GNND program, on the other hand, is specifically designed to provide housing aids to certain professionals such as law enforcement officers, teachers, and emergency medical technicians, with certain housing and loan conditions for each profession.
7. You may need to take a home buyer education course.
Many state and local government programs require participants to complete a homebuyer education class that features content guided by HUD. These “house counseling” classes are designed to help borrowers qualify for a mortgage and teach them to navigate the complicated home buying process. Both first-timers and “boomerang buyers” (those who re-enter homeownership after a past financial hardship or the loss of a home) can benefit from these classes.
A typical class (which can be done online) covers topics such as how much home can you afford, how to comparison shop different real estate agents and lenders, what mortgage product should you consider, how to improve your credit score, and help you settle between your needs and wants especially when house-hunting.
Is down payment assistance available during the coronavirus pandemic?
Technically, yes. Affordable housing programs and other low-down-payment loans and grants are still out there and available. In fact, according to an article from Inman, VA loan activity skyrocketed during the coronavirus pandemic, with the latest data seeing over 330,000 loans issued during the third quarter of 2020.
However, you need to remember that:
Many of the government agencies overseeing these programs, such as the FHA, are overwhelmed right now. They may be facing some financial strains because of their mortgage relief efforts for many homeowners.
There could be a significant slowdown in processing because of the circumstance mentioned above, especially in some areas.
If you really can't get a big enough down payment for a loan, you have to make sure that your credit is as good as possible.
Fitting into the guidelines of any of those down payment assistance programs or low-interest loans can be more challenging than ever before because of the ongoing crisis.
Despite all of these, there’s plenty of optimism to be found amid this recent downturn. Don’t hesitate to ask your real estate professional to know what products are available in your market and ready to be taken advantage of.
Understand the pros and cons of interest-only mortgages to determine if this financing strategy is the right fit for your home buying goals.
In Houston, the question is often not “Should I wait?” It is “What is waiting likely to cost me, and is that tradeoff actually worth it?”
The right strategy depends on your finances, your comfort level, and how competitive the market is in the area where you are buying and selling.
Discover why your driveway is a critical component of your home's curb appeal and how simple updates can boost your property's market value.
Discover why outdoor living spaces are a top priority for luxury home buyers in Houston and how they can transform your property's appeal.
Don't let landscaping costs surprise you. Learn the essential maintenance expenses every home buyer should factor into their budget.
Learn the real reasons homes sit on the market and what sellers can do to attract buyers and sell faster in 2026.
Homeowner
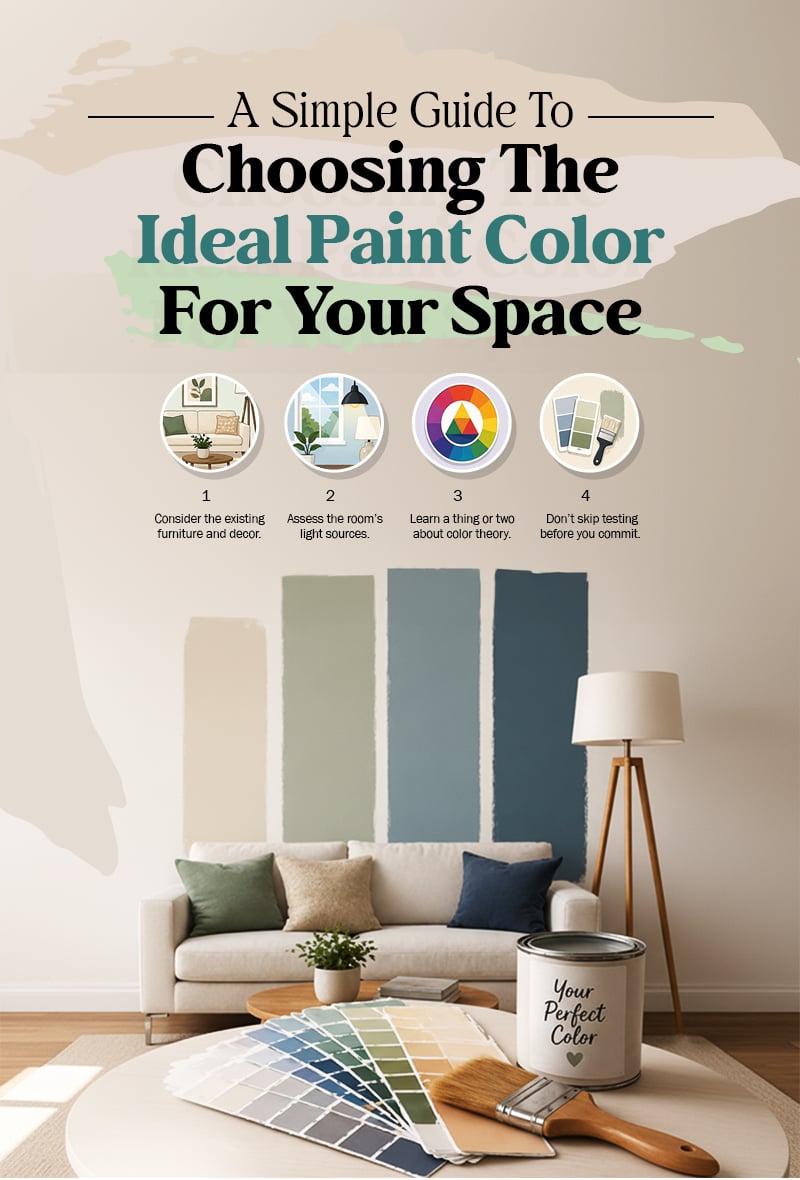
Selecting the ideal paint color can easily transform any space, creating a mood and style that reflects your personality and the room's purpose.
Deciding between repairs and selling as-is? Learn how to maximize your home's value and protect your peace of mind before listing in Houston.
Real estate can feel overwhelming, but you don’t have to navigate it alone. Our team is here to bring clarity to the process, advocate for your goals, and guide you every step of the way.
KRAASE PROPERTY GROUP
1220 AUGUSTA DR HOUSTON, TX 77057