Down Payment Assistance Programs: How Do They Work To Help You Become A Homeowner
Buyer February 12, 2025
Buyer February 12, 2025
Here's a quick guide that will explain what a down payment assistance program is, how it works, and what are the different options that exist to help you reach your goal of owning a home.

Down payment assistance (DPA) is any type of program designed to help home buyers afford a down payment. Some programs also help lower or cover your closing costs. There are thousands of DPA programs available across the country, and the majority of them are offered at state, county, and city levels, and even through some banks and lenders. Down payment assistance is typically geared toward first-time home buyers, but there can also be assistance available for repeat home buyers.
These programs typically have eligibility requirements and borrowers usually have to take out a mortgage with a participating lender to take advantage of their assistance program. The funds often come from the U.S. Department of Housing and Urban Development, or HUD, as well as employers, community organizations, and state and local governments.

Any type of down payment assistance is likely to have certain qualifications. The majority of these programs are geared toward first-time home buyers. A first-time homebuyer is someone who hasn't ever owned a home or hasn’t owned a home in the past three years.
Beyond that, other typical requirements include a minimum credit score of 620, a low-to-moderate household income, and a debt-to-income ratio. Do take note that these requirements vary from program to program. Likewise, many DPA programs also require the following:

Down payment assistance comes in three main types: loans, grants, and credits, each with its pros and cons. Here are some of the most common:
Home buyer grants are the most popular and most valuable form of down payment assistance. This is because it provides homeowners the money that they never have to repay since it's considered a gift. If you qualify, you can use the cash sum to cover all or part of the down payment or closing costs.
However, most grant programs are often more difficult to qualify for due to challenging requirements, such as that you need to live in the home as your primary residence for a certain number of years after your purchase. It’s also important to keep in mind that some programs labeled as grants by the organization providing the funding may create a second lien on your home. Just make sure that you know what you’re getting into and that your lender is aware of the grant.
A forgivable loan is technically a second mortgage large enough to cover the down payment, but it acts as a grant since you don’t have to repay the loan if you meet certain requirements. For example, a program might forgive the loan if you live in the home and pay the primary mortgage for a set amount of time, typically anywhere from three to 10 years. However, if you move, refinance your mortgage, or sell your home before the loan is forgiven, you’ll need to pay it back. Forgivable loans have an interest rate of 0%.
A deferred payment loan most often takes the form of a no-interest second mortgage that typically covers the cost of the down payment. But unlike forgivable loans, you will have to pay back the loan at some point. This happens when you sell the home, refinance your mortgage, or pay off your first mortgage.
This type of down payment assistance also functions as a second mortgage but with a lower or more affordable interest rate than your first loan. Along with making monthly payments for your primary mortgage, you’ll likely need to repay this loan in installments, typically over a few years. This means you’ll be making two monthly mortgage payments.
Also called a matched savings program, an Individual Development Account (IDA) is a unique type of down payment assistance. It’s a special savings account that home buyers deposit money into, which is matched by either a bank, government agency, or community organization. For example, if you put $5,000 into the account, the agency you’re working with would match that amount, making it $10,000. The total funds can then be used to help cover their down payment or other qualifying costs. These programs often have strict requirements to qualify, such as income restrictions, and employment requirements, and participants usually need to complete financial literacy training.

There are many ways to find down payment assistance. Here's where to start:
Private company Down Payment Resource also provides various resources for homebuyers, real estate agents, and lenders, including an eligibility and assistance lookup tool.

Understand that down payment assistance varies from state to local levels, so the amount of time it takes to get one mainly depends on the program and the type of assistance. While the timeline varies, you can expect that it will be a relatively long process.
If you're considering applying for a down payment assistance program, you may want to start looking for your options before you start your home search. This is so you can give yourself plenty of time. If you’re required to take a first-time home buyer course or a financial literacy course, you can still complete it within the dedicated timeframe.
Understand the pros and cons of interest-only mortgages to determine if this financing strategy is the right fit for your home buying goals.
In Houston, the question is often not “Should I wait?” It is “What is waiting likely to cost me, and is that tradeoff actually worth it?”
The right strategy depends on your finances, your comfort level, and how competitive the market is in the area where you are buying and selling.
Discover why your driveway is a critical component of your home's curb appeal and how simple updates can boost your property's market value.
Discover why outdoor living spaces are a top priority for luxury home buyers in Houston and how they can transform your property's appeal.
Don't let landscaping costs surprise you. Learn the essential maintenance expenses every home buyer should factor into their budget.
Learn the real reasons homes sit on the market and what sellers can do to attract buyers and sell faster in 2026.
Homeowner
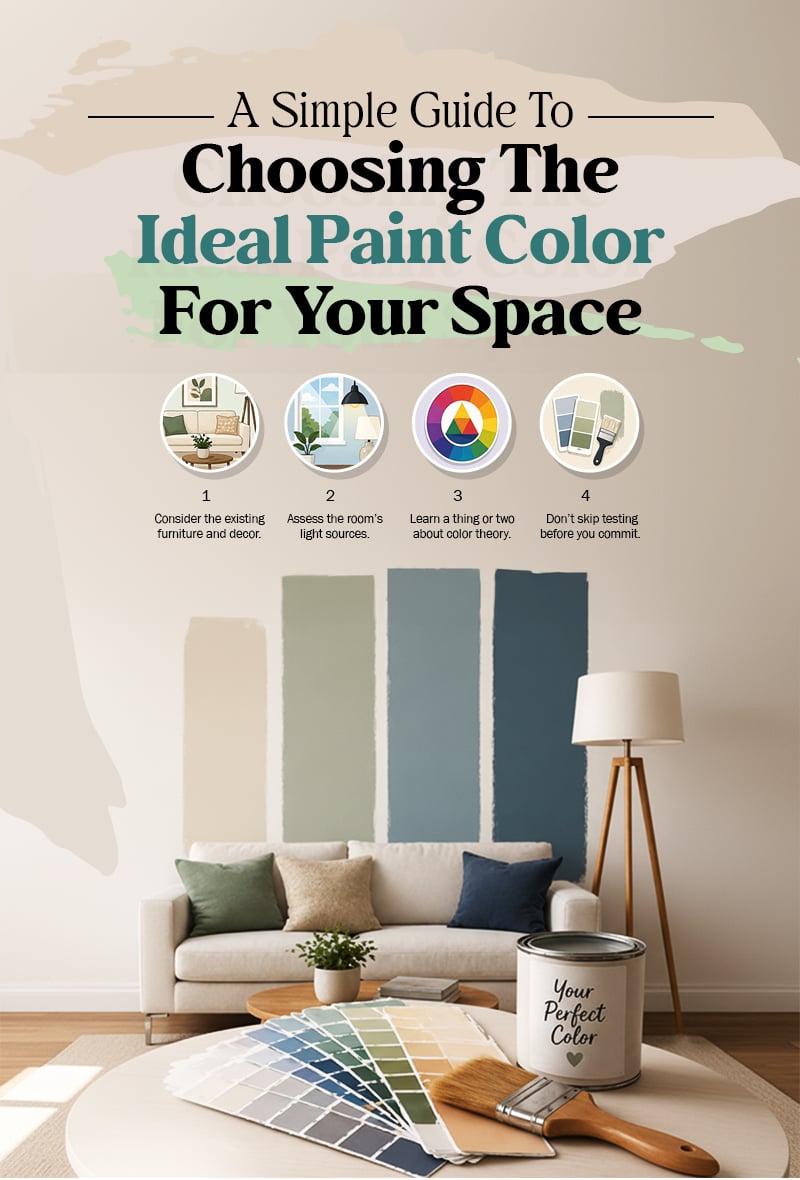
Selecting the ideal paint color can easily transform any space, creating a mood and style that reflects your personality and the room's purpose.
Deciding between repairs and selling as-is? Learn how to maximize your home's value and protect your peace of mind before listing in Houston.
Real estate can feel overwhelming, but you don’t have to navigate it alone. Our team is here to bring clarity to the process, advocate for your goals, and guide you every step of the way.
KRAASE PROPERTY GROUP
1220 AUGUSTA DR HOUSTON, TX 77057