Here's What You Need To Know About the Mortgage Underwriting Process
February 15, 2024
February 15, 2024
When going through the mortgage approval process, one aspect you need to keep in mind is underwriting. Once you've been pre-approved for a loan your application moves from the desk of your loan officer to the mortgage underwriter who will further investigate your financial profile to make sure it matches your lender’s guidelines and loan criteria. The underwriting process plays a huge role in whether your loan request will be approved or denied.
Mortgage underwriting, or Real Estate underwriting, is the process in which mortgage lenders verify your assets and credit-worthiness to get a home loan. All loans go through this step before the lender can give you the funds for a mortgage. It can be as quick as two to three days, but typically takes over a week to finish and happens right before closing.
Mortgage underwriting standards have become more heavily regulated because of additional requirements enacted by the Consumer Financial Protection Bureau (CFPB) after the 2008 housing market crash.
The underwriter plays a huge role in whether or not you can get the mortgage for your dream home. Some of the underwriter's responsibilities include:
Assessing your risk as a borrower and making sure you meet the lender’s guidelines
Reviewing and confirming your application and documentation, employment, and financial history
Making sure all documents are present and accurate according to mortgage industry standards
Underwriters assess your risk by typically reviewing your documentation and paperwork, such as tax returns, W-2s, bank statements, asset statements, pay stubs, savings, IRA accounts, and other basic documents. They may also request specific documents depending on the type of loan you're getting. If you are self-employed, you may also need to provide more detailed documentation of your income and work status.
Underwriters will also pay attention to your debt-to-income (DTI) ratio to make sure you have enough money to cover your current financial obligations even if you’ll take on a mortgage.
Your credit score is one of the most important factors in your mortgage loan approval. You need to have a solid credit history to show that aside from being financially capable you're also a responsible borrower. Since your credit score is important, the underwriter will look closely at your credit report to see how you have handled past bills and credit, such as credit card payments, car loans, or student loans.
In addition, the underwriter will review the type of property you are looking to buy, its value, and how the property is used. Different types of properties carry different risks, especially when it comes to investment properties. So the lender needs to make sure that the loan amount meets the loan-to-value requirements of the product. He or she will typically order a home appraisal to determine the objective value of the home.
While the mortgage underwriting process can vary according to lenders and the institution they belong to, all lenders will most likely involve these three C's when assessing your risk as a potential borrower. Understanding these factors can help you understand what to expect with the process for you to have a better chance of getting a mortgage.
Underwriting takes place behind closed doors. If your underwriting is rejected your loan officer or mortgage broker will relay any requests for additional documents or further explanations. You can provide the additional documents to get your loan process back on track, such as an explanation for a recent huge bank deposit or withdrawal, or further documents to verify your income and employment.
However, if your underwriting was denied due to problems like a low credit score, high DTI ratio, and insufficient cash reserves, it might take time to resolve these problems before you can complete the loan approval.
While mortgage underwriting can be very complicated and frustrating for any potential borrower, there are steps you can take to allow your loan application to sail through as smoothly as possible:
Make sure your paperwork is complete.
Respond promptly to your underwriter's request for more information and supporting documents.
Protect and maintain a good credit score during the entire process and until you close on the home.
Keep in touch with your lender and/or mortgage broker to check on the status of your application.
Understand the pros and cons of interest-only mortgages to determine if this financing strategy is the right fit for your home buying goals.
In Houston, the question is often not “Should I wait?” It is “What is waiting likely to cost me, and is that tradeoff actually worth it?”
The right strategy depends on your finances, your comfort level, and how competitive the market is in the area where you are buying and selling.
Discover why your driveway is a critical component of your home's curb appeal and how simple updates can boost your property's market value.
Discover why outdoor living spaces are a top priority for luxury home buyers in Houston and how they can transform your property's appeal.
Don't let landscaping costs surprise you. Learn the essential maintenance expenses every home buyer should factor into their budget.
Learn the real reasons homes sit on the market and what sellers can do to attract buyers and sell faster in 2026.
Homeowner
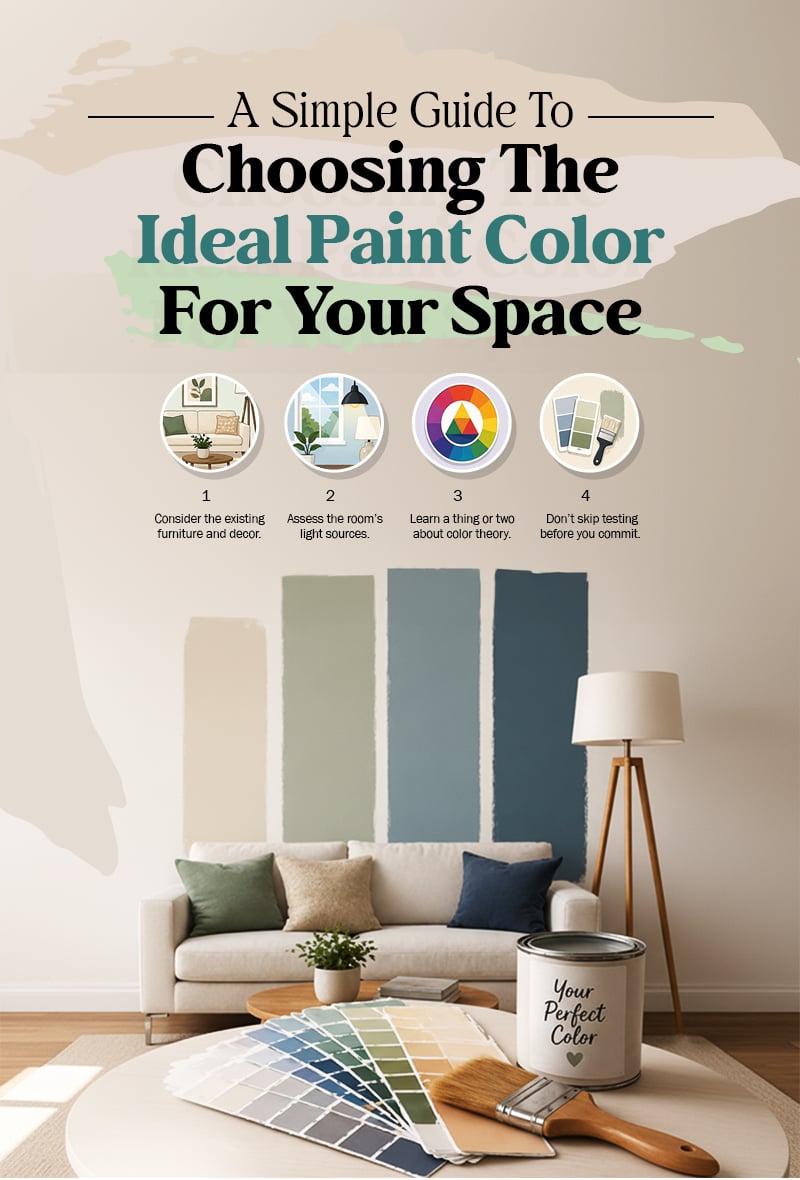
Selecting the ideal paint color can easily transform any space, creating a mood and style that reflects your personality and the room's purpose.
Deciding between repairs and selling as-is? Learn how to maximize your home's value and protect your peace of mind before listing in Houston.
Real estate can feel overwhelming, but you don’t have to navigate it alone. Our team is here to bring clarity to the process, advocate for your goals, and guide you every step of the way.
KRAASE PROPERTY GROUP
1220 AUGUSTA DR HOUSTON, TX 77057