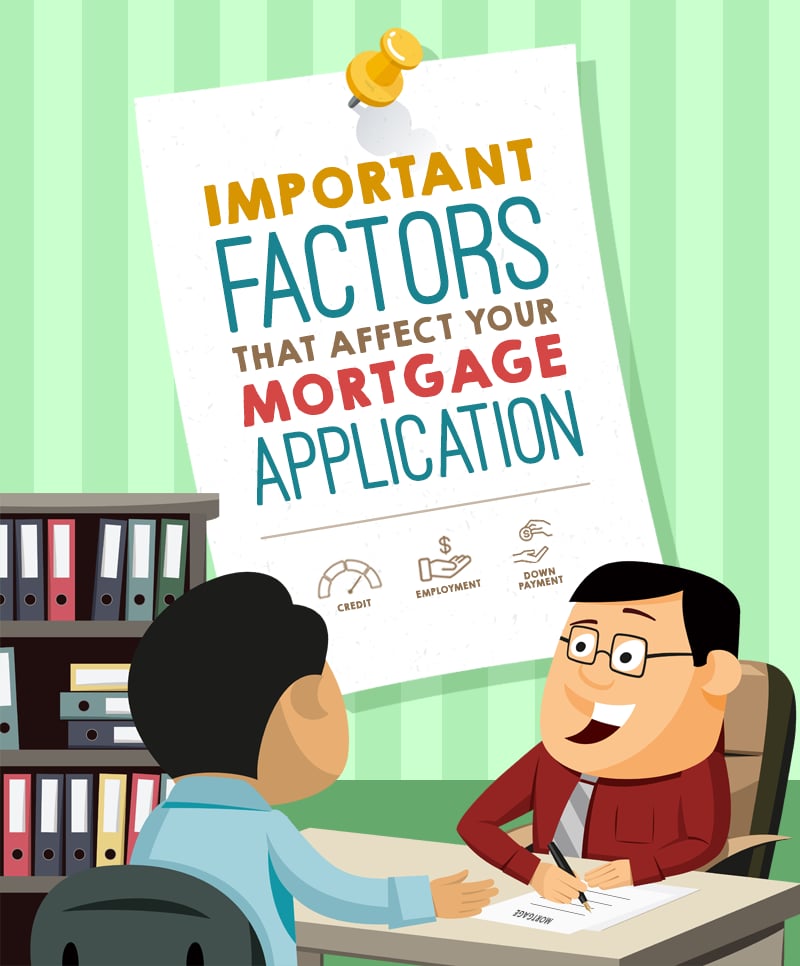
Important Factors That Affect Your Mortgage Application
June 8, 2018
June 8, 2018

Financial health is one of the most important considerations for mortgage qualification, and is mainly determined by your credit score. Typically, the higher your score, the lower your interest rates will be. When your credit score falls below 740, it may be challenging for you to qualify for a conventional mortgage. Lower credit scores may leave you with subprime options with high interest rates.

Be prepared!
Know your credit score before applying for a mortgage. To have a clear idea of your status, request a copy of your credit report from the three major reporting agencies (TransUnion, Experian, Equifax) and analyze where you stand. Identify all the problem areas in your report and take the necessary actions in order to improve them.
For example, if there are inaccurate, incomplete, or unverifiable items in your report, dispute them immediately by providing the credit bureau enough information to investigate. If you have small balances on several credit cards, start paying them off. Finally, pay your bills on time and avoid incurring any new debt. It may take a few months to make a significant impact on your score, but it will all be worth it once you're ready to apply for a mortgage.

When applying for a mortgage, lenders consider your income just as much as your assets. Meaning--your readiness to buy a home is measured not just by how much money you've saved up for a down payment, but also by how much money you make on a monthly basis.
When it comes to loan eligibility in terms of income, lenders will consider your combined income from all sources, taking the following into account: alimony, child support payments, retirement benefits, investment returns, bonuses, and other regularly occurring payments. But for most applicants, their monthly paycheck makes up the bulk of their loan-eligible income.

Be prepared!
A strong employment history indicates stability and proves that you have the means to settle your monthly dues. If you've been with the same employer and in the same field for two years or more, lenders are more likely to consider your application. If you have these qualifications, avoid taking on a new job before closing, as this may negatively affect the status of your application. Remember, you will be asked for proof that you are currently employed, and the lender may even have to reach out to your employer for verification.
In other cases, you may need to have a different approach:
If you've already changed jobs, be sure to explain your reasons in detail. Mortgage professionals need to be sure that your new position won’t have a detrimental effect on your income, so prepare the necessary documents to prove that the change is actually a wise decision or a step up in your career. If you are staying in the same field (better if you’re accepting a pay raise or promotion), then it won’t really be a problem.
If you have variable income or employment gaps, you may need to provide detailed documentation of your cash flow over the past two years. It also pays to be aware that lenders may need to take a more conservative approach when calculating your total monthly income.
For self-employed workers, it is advisable to prepare two years’ worth of accounts and/or tax returns, a track record of regular work, bank statements that can show a consistent stream of healthy deposits, as well as a good credit report. Also, take our word for it and hire a certified accountant to do the work for you. It adds legitimacy to your claims and shows lenders that you’re serious about getting a loan you can afford.
However, if you don’t have a record of two years of accounts, don’t worry--not all hope is lost! Lenders will still consider your application as long as you have evidence of work lined up for you in the foreseeable future, especially if you have a history of working in the same field as a regular employee before venturing into full-time freelance work.
Important note for all mortgage applicants, whether you have a regular job or are self-employed: Be sure that you’re buying a property with combined monthly payments (which includes insurance and property taxes) that add up to 1/3 (or even less!) of your monthly income. Lenders are wary of approving loans that will result in borrowers using half of their income just to pay it off.

Once you've already established your capability to repay the loan on a monthly basis, the next thing you’ll have to be prepared to show is the money you can pay NOW. Lenders are most likely to approve a loan when the home buyer applying for it is able to pay at least a 20% down payment. Of course--the higher you can go, the better.

Be prepared!
While a 20% down payment is generally the standard of being a capable buyer, lenders are more likely to consider borrowers who can put down more than that. If you have a solid understanding of using an escrow account, this can also win you points as well.
Why should the lender care about how much down payment you can afford? Well, having a sizeable down payment for your new home reduces the risk for the lender as it gives you instant equity to the home. It also says a lot about your ability to save up a hefty amount of cash--which means that you have a better chance at making balloon payments to pay off the loan early.
If you don't have 20% down payment saved up, this doesn’t mean you won’t get approved. However, you will likely be required to pay for private mortgage insurance (PMI) if your down payment is 10% or lower. The good news is that if you have good credit, you can get by with a small down payment (some lenders require only 3 or 5%).
Just remember: When applying for a loan, you can always work with what you have as long as you know how to leverage your strengths.
Understand the pros and cons of interest-only mortgages to determine if this financing strategy is the right fit for your home buying goals.
In Houston, the question is often not “Should I wait?” It is “What is waiting likely to cost me, and is that tradeoff actually worth it?”
The right strategy depends on your finances, your comfort level, and how competitive the market is in the area where you are buying and selling.
Discover why your driveway is a critical component of your home's curb appeal and how simple updates can boost your property's market value.
Discover why outdoor living spaces are a top priority for luxury home buyers in Houston and how they can transform your property's appeal.
Don't let landscaping costs surprise you. Learn the essential maintenance expenses every home buyer should factor into their budget.
Learn the real reasons homes sit on the market and what sellers can do to attract buyers and sell faster in 2026.
Homeowner
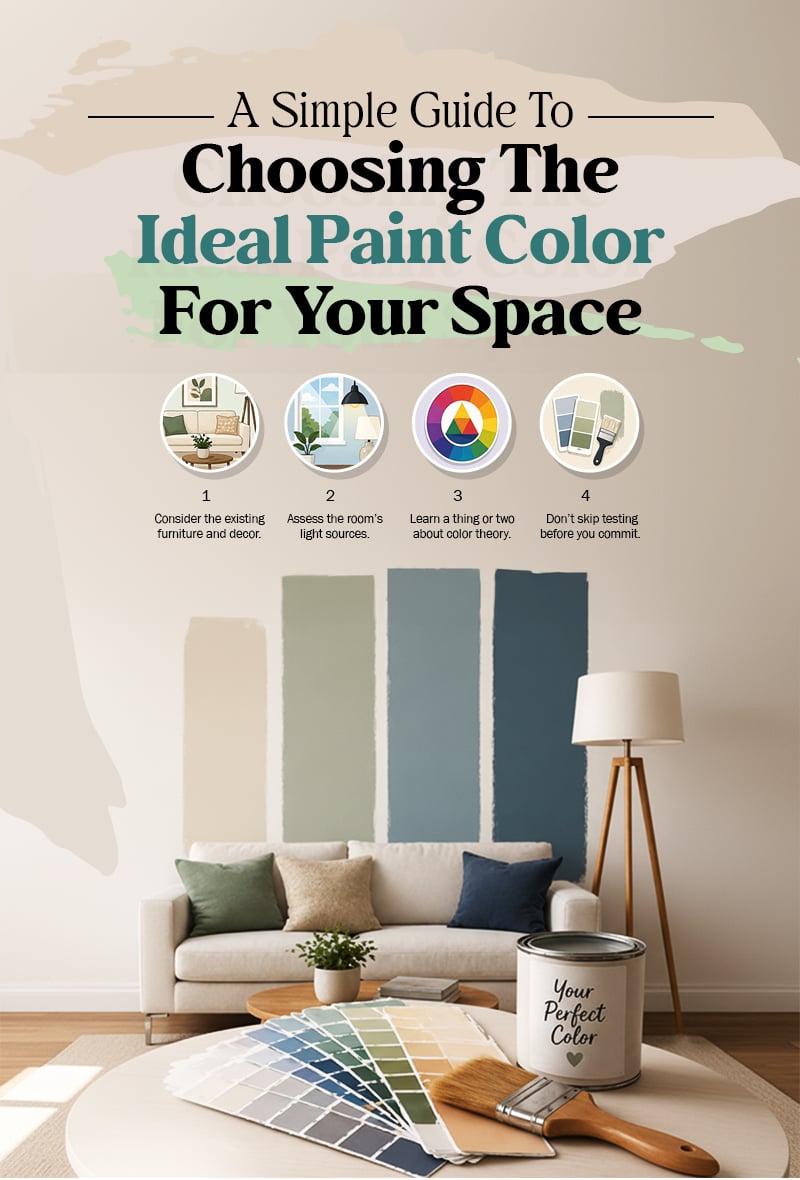
Selecting the ideal paint color can easily transform any space, creating a mood and style that reflects your personality and the room's purpose.
Deciding between repairs and selling as-is? Learn how to maximize your home's value and protect your peace of mind before listing in Houston.
Real estate can feel overwhelming, but you don’t have to navigate it alone. Our team is here to bring clarity to the process, advocate for your goals, and guide you every step of the way.
KRAASE PROPERTY GROUP
1220 AUGUSTA DR HOUSTON, TX 77057